Thursday, 16 March 2006

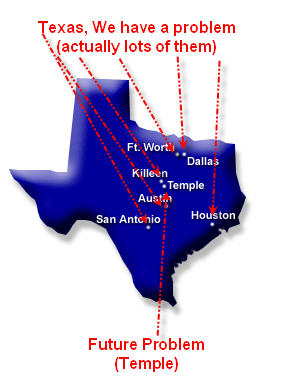
Houston, We have a problem

Note: The page header may not refresh properly on the following links but the data itself should represent the correct city.

Houston, We have a problem
It seems Centex has over 140 Houston homes with "quick move in" availability. Nearly all of them are available "immediately".

Austin, We have a problem
It seems Centex has over 100 Austin homes with "quick move in" availability. Nearly all of them are available "immediately".

Dallas, We have a problem
It seems Centex has over 200 Dallas / Fort Worth with "quick move in" availability. Most of these will be available within the next couple months.

Killeen, We have a problem
It seems Centex has over 65 Killeen homes with "quick move in" availability. Most of these will be available within the next couple months.

San Antonio, We have a problem
It seems Centex has over 190 San Antonio homes with "quick move in" availability. Most of these will be available this summer but there is an ample selection now and over the next couple of months as well.

Hmmm. Let's see that's about 700 Texas homes Cextex needs to get rid of in the face of declining sales and rising inventories. Bear in mind that is just Texas. Let's look elsewhere:

Orlando, We have a problem
It seems Centex has over 25 Orlando Homes with "quick move in" availability. Most of these will be available by the end of March.

Tampa, We have a problem
It seems Centex has over 40 Tampa homes with "quick move in" availability. Availability of these homes is widely spaced out.

Chicago, We have a problem
It seems Centex has over 20 Chicago homes with "quick move in" availability. Availability of these homes is widely spaced out.

It would take me too long to go through every state but you can look up your favorite locations on this Centex US Map. Just click on your favorite city, then on "Homes ready for quick move in" to find the current state of inventory.

Centex is clearly carrying a lot of speculative inventory and further price reductions should be expected. I can easily summarize the situation:
Centex, You have a problem.

It is not just Centex either.
Checking every builder, it appears "immediate move in", "homes available now" etc are new pages on their websites.

Beazer has 17 pages of "Homes Available Now" for Houston. Unfortunately it also lists homes under contract making it more time costly to figure out real inventory vs. what has already been sold. Click on "Find Your Home" to check out your favorite bubble areas, state by state.

Meritage Texas "Quick Move Ins":
Meritage has 118 "Quick Move Ins" for Austin
Meritage has 94 "Quick Move Ins" for Dallas / Fort Worth
Meritage has 99 "Quick Move Ins" for Houston
Meritage has 18 "Quick Move Ins" for San Antonio

Enquiring minds may wish to start with the Meritage home page to look at other locations.

I have time for one telepathic question.
This one just came in: "Mish, what about Naples Florida?"
Hmmm. Good Question.

The Naples Sun Times is asking Sellers, are you ready for the news?
In February 2006 there were 5,417 single family homes listed for sale in the Sunshine Multiple Listing Service (MLS) of the Naples Area Board of Realtors, of which 204 sold. There were 5, 289 condos/coops for sale, of which 179 sold.

Let's do the math: 5,417 plus 5,289 equals 10,706. Divide that by 383, which is the number of homes that sold (204 plus 179). What do you get? 27.95? That means that in February there was a 28-month supply of homes for sale. In other words, if no other homes came on the market, it would take 28 months for all homes listed for sale to be sold.

What is the likelihood that no more homes will come on the market? And these figures don't reflect homes sold or offered for sale not listed on the MLS.
Naples, you have a big, big problem.
In fact, there are inventory problems nearly everywhere you look.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Mideast Contagion?

The Washington Post is reporting Gulf Markets Hit With Widespread Selling.
DUBAI, United Arab Emirates -- The relatively new stock markets in the Gulf have been getting a lesson in the old stock market saw that no market rises forever.

Bourses in Dubai, Saudi Arabia, Qatar, Oman and Bahrain have dropped recently, after soaring oil prices and strong economic growth over the past few years pushed shares into overvalued territory, analysts said.

The Dubai Financial Market has taken one of the worst drubbings, dropping nearly 2 percent on Wednesday after losing 11 percent on Tuesday, the worst one-day loss in the market's history. Stock market losses in the Gulf have been so sharp that Kuwaiti investors angered by the slump held a rare, but peaceful protest Tuesday urging the government to intervene.

"After a stellar performance for the past few years in which most of these markets have shown an increase of more than a 1,000 percent, it was inevitable for a correction to take place," said economist Beshr Bakheet of the Saudi-based Bakheet Financial Advisers.

Early Wednesday trade in the DFM had seen a short-lived bounce of up to 5 percent, a result of snap-up bargains following Tuesday's drop, which was partly triggered by the plunge in oil-rich Saudi Arabia's stock market.

The DFM closed Wednesday at 599.88 points, down 1.96 percent from Tuesday's close.

In neighboring Saudi Arabia, the region's largest market, the benchmark Tadawul index on Tuesday dropped another 5 percent, the maximum allowed by regulators, bringing the market down by a quarter over the past three weeks.

The selloff continued in early trade Wednesday, with the index down another 4.86 percent, or 723.54 points at 14,176.5. The market recovered slightly by the day's end, closing at 15,606.57, up 706.53 points, or 4.74 percent higher than Tuesday's close.

Saudi authorities on Tuesday scotched speculation that the government would intervene to protect investors caught out by days of declining prices, with a government-run think tank in the United Arab Emirates urging against such action.

"Any direct government intervention to affect prices will have long-term negative effects," the Emirates Center for Strategic Studies and Research said. "Governments must free the markets and consolidate transparency. The reality of what the market is going through poses an urgent need to make room for the market mechanism to operate in total transparency."

Bakheet also objected to calls for government intervention.

"Governments should not interfere or intervene, on the way up or the way down, because this is a free economy. You can't prevent investors or speculators from throwing their money at bad stocks. All you can tell them is this is not the right way to do it," he said.

Saudi billionaire Al-Waleed bin Talal said Wednesday he was planning to prop up the market with a cash injection of up to 10 billion riyals ($2.6 billion).

The Saudi market decline also prompted Saudi King Abdullah to call on authorities to allow non-Saudis to deal in the market, in an apparent attempt to inject more funds into the market.

Previously, non-Saudis were restricted to dealing in investment funds.
Trade Arabia is reporting Prince vows $2.7bn investment amid market crash
Saudi Arabia’s Prince Alwaleed bin Talal said his firm, Kingdom Holding, will invest SR5-SR10 billion ($1.3-2.7 billion) in the Saudi bourse after the current correction he blamed on speculators. His pledge came as analysts said a strong correction that had hit the Saudi stock market and others in Gulf states would continue for several weeks.

'It (Kingdom) will allocate 5 or 10 billion to enter the market,' the prince told Al Arabiya television. 'There are now special and great opportunities,' he added.

Reports, meanwhile, said the value of Gulf bourses dropped today to around $900 billion down some $200 billion from their 2005 value and more than $300 billion below the peak.

Prince Alwaleed said Saudi economy was strong and that speculators caused the stock market's 'plight' by driving weak shares up to unjustified levels. 'What happened a few months ago on the Saudi market is that speculators dominated the market and created a bubble,' he was quoted as saying in a Reuters report.

A two-week long correction has trimmed the capitalisation of the bourse by more than 31 per cent.

Saudi shares rebounded more than four per cent after Alwaleed's comments and an announcement by the Finance Ministry that Saudi Arabia was mulling allowing foreign residents to invest directly on the local bourse and lowering the nominal value of shares.

Alwaleed welcomed the proposals by King Abdullah. 'Splitting shares is beneficial and allowing foreign residents (to invest) is a very good decision,' he said. The prince warned against speculation for short-term gain. 'The profit factor now is very strong ... There are many solid and respectable Saudi firms which derive their strength from that of the Saudi economy,' he said.

'The stock market in any country is a reflection of the economy. The Saudi economy is very strong and this gives reassurances and encourages the Saudi investor to return (to the market), buy and participate in companies that are respectable and have a (good) history.'

The prince also urged the Capital Markets Authority to expedite the listing of firms to absorb excess liquidity. 'There is a lot of liquidity in Saudi Arabia but not many investment opportunities.'

Panic among the majority of small Saudi investors pushed many of them to sell their stocks, which greatly contributed to the slide.

The Abu Dhabi Securities Market dropped below the 4,000-point mark to close at 3,986.96 points, down 0.85 per cent yesterday’s close. It has so far lost 23.4 per cent on the end-2005 close of 5,202.95 points and 37.7 per cent on its all-time high.

The Kuwait Stock Market dropped 1.1 per cent to close below the 10,000-point mark at 9,939.30 points, 13.2 per cent below its 2005 close of 11,445.10 points.

The Doha Securities Market dropped below the 9,000-points mark to close down 4.4 per cent at 8,873.08 points. It is 19.7 per cent below last year's close of 11,053.24 points.
It's Mish question time:
  1. Is this similar to the attempts to prop up the US markets by bankers in 1929?
  2. Why would one want to prop up speculation anyway?
  3. Non-Saudis can invest in their market now that it is tanking. Excuse me but who wants to?
  4. Since the Mideast is busy propping up their own markets, does that mean they will have less cash to buy ours?
  5. Is this some sort of "Mideast Contagion" similar to the "Asian Contagion"?
  6. Is this page 15 news that will stay on page 15 or a Harbinger of things to come elsewhere?
Some of the answers will become readily apparent in due time but there is one thing we know for sure right now: intervention to prop up markets never works.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Monday, 13 March 2006

The Sorry State of US Govt Accounting Practices

I just finished reading the US Government’s consolidated financial statements for the fiscal year ending September 30, 2005.

If you wish to read the full report, be forewarned that it is a 158 page PDF.
Following are some interesting snips. Notes:
1)Page number refers to the PDF page number not the page on the Government report
2)Click on any chart for a larger view (the first one is already full size)

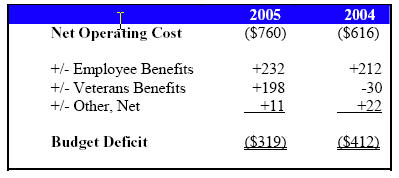
Starting off on page 14 we see a budget deficit of $319 Billion.


Disclaimers

On pages 31-33 we find these disclaimers by the US Government Accountability Office:
  • Material deficiencies in financial reporting (which also represent material weaknesses and other limitations on the scope of our work resulted in conditions that, for the ninth consecutive year, prevented us from expressing an opinion on the federal government’s consolidated financial statements.
  • The federal government did not maintain effective internal control over financial reporting (including safeguarding assets) and compliance with significant laws and regulations as of September 30, 2005.
Three major impediments to our ability to render an opinion on the consolidated financial statements continued to be
(1) serious financial management problems at the Department of Defense,
(2) the federal government’s inability to adequately account for and reconcile intragovernmental activity and balances between federal agencies, and
(3) the federal government’s ineffective process for preparing the consolidated financial statements.

Moreover, as a result of the material deficiencies we found, readers are cautioned that amounts reported in the consolidated financial statements and related notes, certain information contained in the accompanying Management’s Discussion and Analysis, and other financial management information that is taken from the same data sources as the consolidated financial statements, may not be reliable. Until the problems discussed in our audit report are adequately addressed, they will continue to have adverse implications for the federal government and the taxpayers, which are outlined in our report.

More troubling still, the federal government’s financial condition and long-term fiscal outlook is continuing to deteriorate. While the fiscal year 2005 budget deficit was lower than 2004, it was still very high, especially given the impending retirement of the “baby boom” generation and rising health care costs. Importantly, the federal government’s accrual based net operating cost increased to $760 billion in fiscal year 2005 from $616 billion in fiscal year 2004.

The current financial reporting model does not clearly and transparently show the wide range of responsibilities, programs, and activities that may either obligate the federal government to future spending or create an expectation for such spending. Thus, it provides a potentially unrealistic and misleading picture of the federal government’s overall performance, financial condition, and future fiscal outlook. The federal government’s gross debt in the consolidated financial statements was about $8 trillion as of September 30, 2005.

This number excludes such items as the gap between the present value of future promised and funded Social Security and Medicare benefits, veterans’ health care, and a range of other liabilities (e.g., federal employee and veteran benefits payable), commitments, and contingencies that the federal government has pledged to support. Including these items, the federal government’s fiscal exposures now total more than $46 trillion, up from about $20 trillion in 2000. This translates into a burden of about $156,000 per American or approximately $375,000 per full-time worker, up from $72,000 and $165,000 respectively, in 2000. These amounts do not include future costs resulting from Hurricane Katrina or the conflicts in Iraq and Afghanistan. Continuing on this unsustainable path will gradually erode, if not suddenly damage, our economy, our standard of living, and ultimately our national security.

Addressing the nation’s long-term fiscal imbalance constitutes a major transformational challenge that may take a generation or more to resolve. Given the size of the projected deficit, the U.S. government will not be able to grow its way out of this problem—tough choices are required.
The above notes were signed off by David M. Walker, Comptroller General of the United States.

Gross and Net Costs by Department

On page 40 there is a nice table of gross and next expenditures by departments:


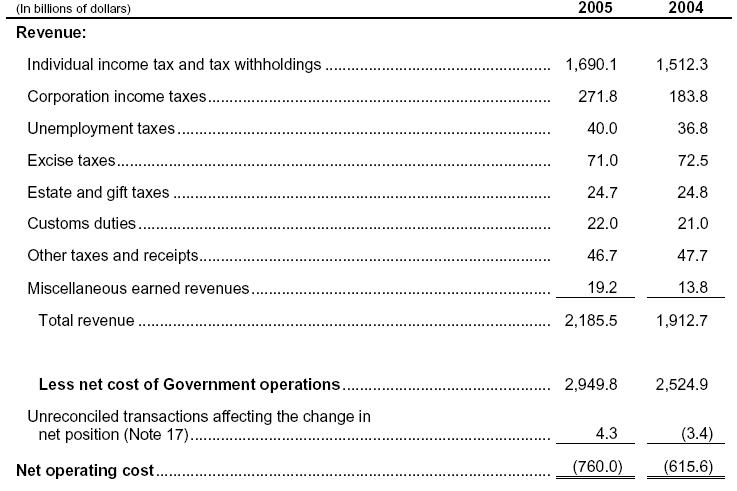
Revenue vs. Spending

The following table shows that we are currently spending $760 Billion more than we take in. Furthermore, you can clearly see that taxpayers as opposed to corporations are bearing the big brunt of government spending.


Unfunded Liabilities

A Mish telepathic question just came in:
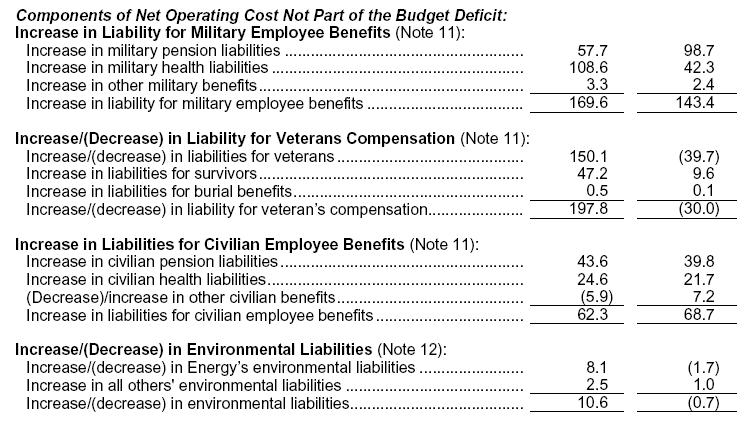
Why is the budget deficit reported as $319 billion and not $760 billion?
It just so happens there is an answer to this question on page 42.

Table of Unfunded Liabilities (partial table shown here)


The government cleverly subtracts unfunded liabilities from the budget
as if they do not matter. This results in ....
Unified Budget Deficit.............. (318.5) (412.3) for 2005 2004

Heck, it seems we could balance the budget overnight with this insane accounting practice.
All we have to do is not fund another $318.5 billion in liabilities. Voila. Balanced Budget.

Assets

Page 44 has a nice table of assets.


Back on Page 15 is this note tucked away about assets.
The Government’s total assets increased from $1,397.3 billion as of the end of fiscal year 2004 to $1,456.1 billion as of the end of fiscal year 2005. This increase was due to increases in all of the Government’s assets except its cash and other monetary assets, which declined slightly. Representing almost 50 percent of total assets this fiscal year, net property, plant, and equipment has been the Government’s largest asset over the past 7 fiscal years. In fact, the reported value of these assets increased substantially in fiscal year 2003 as a result of a change in Federal accounting standards. This change resulted in the recognition of a net book value of $325.1 billion in military equipment being presented on the balance sheet for the first time.
Liabilities


Social Security
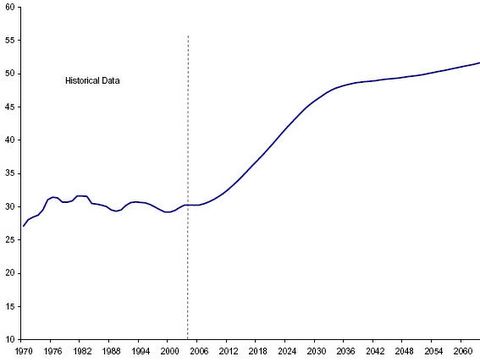
In 2004, there were about 30 beneficiaries for every 100 workers. By 2030, there will be about 46 beneficiaries for every 100 workers. A similar demographic pattern confronts the Medicare Program. For example, for the HI Program, there were about 26 beneficiaries for every 100 workers in 2004; by 2030 there are expected to be about 42 beneficiaries for every 100 workers. This ratio for both programs will continue to increase to about 50 beneficiaries for every 100 workers by the end of the projection period, after the baby-boom generation has moved through the Social Security system due to declining birth rates and increasing longevity.
A chart for Social Security showing the number of beneficiaries per 100 workers can be found on page 54:


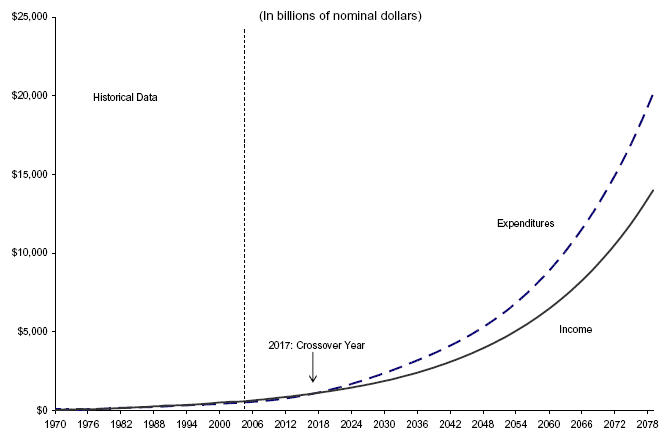
Social Security Expenditures minus Income


Currently, Social Security tax revenues exceed benefit payments and will continue to do so until 2017, when revenues are projected to fall below benefit payments, after which the gap between expenditures and revenues continues to widen.

Medicare Projections

On December 8, 2003, President Bush signed into law the Medicare Prescription Drug, Improvement, and Modernization Act of 2003. The 2003 law will have a major impact on the operations and finances of Medicare. The law adds a prescription drug benefit to Medicare beginning in 2006 and a new prescription drug account in the SMI Trust Fund. The benefit could be obtained through a private drug-only plan, a private preferred-provider organization or health maintenance organization, or through an employer-sponsored retiree health plan. The preferred-provider organizations will be new to the Medicare Program and will operate on a regional basis. The Federal Government will assume some of the costs of providing prescription drug coverage to people eligible for both Medicare and Medicaid.

The legislation also includes provisions not related to the prescription drug benefit. It includes increases in Medicare provider reimbursements, higher Medicare Part B premiums for people at higher income levels, and an expansion of tax-deductible health savings accounts. The 2003 legislation is expected to have a significant effect on future Medicare finances as seen below and earlier in the Statement of Social Insurance.

Health Care Cost Growth

In addition to the growth in the number of beneficiaries per worker, the Medicare Program has the added pressure of expected growth in the use and cost of health care per person. Continuing development and use of new technology is expected to cause health care expenditures to grow faster than GDP in the long run. For the intermediate assumption, health care expenditures per beneficiary are assumed to grow one percentage point faster than per capita GDP over the long range.

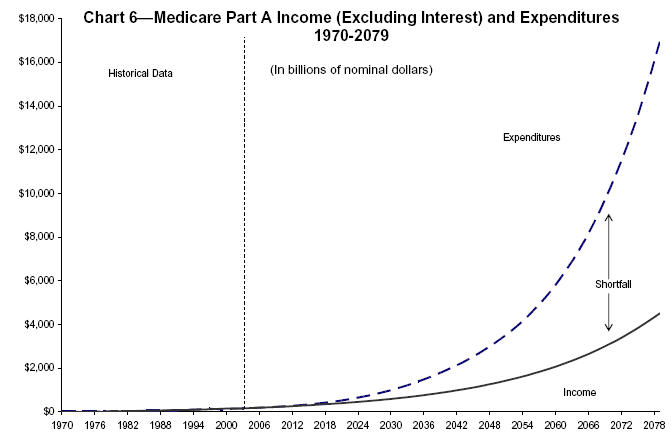
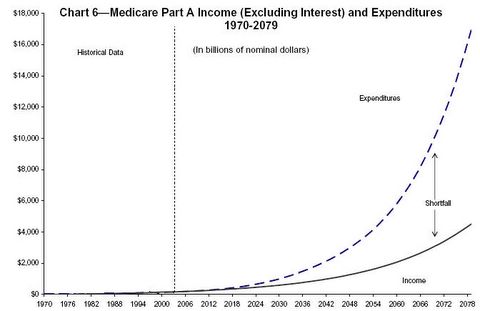
The following chart shows Medicare, Part A (Hospital Insurance) - Nominal Income and Expenditures. Medicare Part A funds the cost of inpatient hospital and related care for individuals age 65 or older who meet certain insured status requirements, and eligible disabled people. The program is financed primarily by payroll taxes, including those paid by Federal agencies. It also receives income from interest earnings on Treasury securities and a portion of income taxes collected on Social Security benefits.

The chart can be found on page 61. It shows historical and actuarial estimates of HI annual income (excluding interest) and expenditures for 1970-2079 in nominal dollars. The estimates are for the open-group population. The figure reveals a widening gap between income and expenditures after 2004.

Medicare Part A Expenditures minus Income

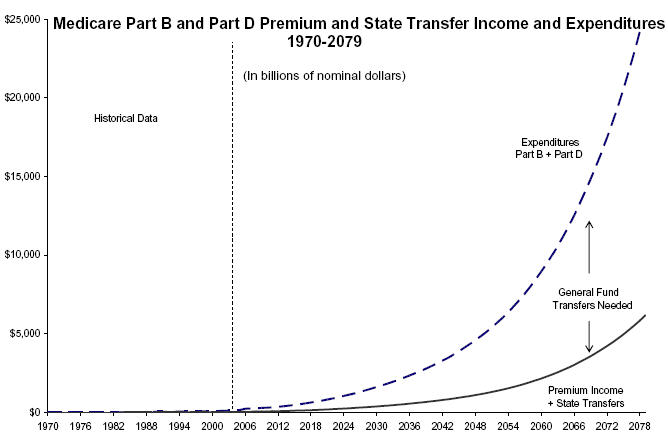
The following chart shows Medicare Parts B and D (Supplementary Medical Insurance).
Medicare Part B provides supplementary medical insurance for enrolled eligible participants to cover physician and outpatient services not covered by Medicare Part A. Medicare Part B financing is based on monthly premiums and income from the General Fund of the Treasury. The chart can be found on page 64. It shows historical and actuarial estimates of Medicare Part B and Part D premiums (and Part D State transfers) and expenditures for each of the next 75 years, in nominal dollars. The gap between premiums and State transfer revenues and program expenditures grows throughout the projection period. That gap that will need to be filled with transfers from general revenues.

Medicare Parts B & D Expenditures minus Income
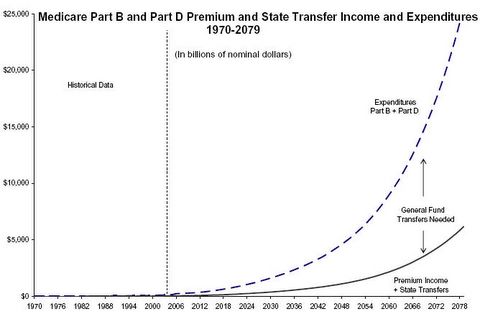


The above charts show that the expenditure rate exceeds the income rate beginning in 2004, and cash deficits continue thereafter.
Trust fund interest earnings and assets provide enough resources to pay full benefit payments until 2020 with general revenues used to finance interest and loan repayments to make up the difference between cash income and expenditures during that period. Pressures on the Federal budget will thus emerge well before 2020. Present tax rates would be sufficient to pay 79 percent of scheduled benefits after trust fund exhaustion in 2020 and 27 percent of scheduled benefits in 2079.


Gold

On page 89 we find the only possible bright spot. It seems the government has undervalued our gold by as much as $350-$400 per ounce at current prices.
Gold is valued at the statutory price of $42.2222 per fine troy ounce. The number of fine troy ounces was 258,713,310 as of September 30, 2005, and 2004. The market value of gold on the London Fixing as of the reporting date was $473 and $416 per fine troy ounce for the years ended September 30, 2005, and 2004, respectively. Gold totaling $10.9 billion for the years ending September 30, 2005, and 2004, was pledged as collateral for gold certificates issued and authorized to the FRBs by the Secretary of the Treasury. Treasury may redeem the gold certificates at any time.
Other Liabilities

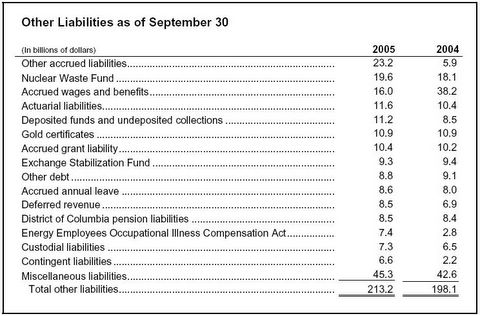
On page 109 is a table of "Other Liabilities".


Trust Funds
  • Federal Old-Age and Survivors Insurance Trust Fund
  • Civil Service Retirement and Disability Fund
  • Federal Hospital Insurance Trust Fund (Medicare Part A)
  • Federal Disability Insurance Trust Fund
  • Medicare-Eligible Retiree Health Care Fund
  • Unemployment Trust Fund
  • Federal Supplementary Medical Insurance Trust Fund (Medicare Part B)
  • Railroad Retirement Trust Fund
  • Land and Water Conservation Fund
  • Foreign Service Retirement and Disability Fund
  • National Service Life Insurance Fund
  • Airport and Airway Trust Fund
  • Highway Trust Fund
  • Hazardous Substance Superfund
  • Black Lung Disability Trust Fund
  • Indian Trust Funds
A description of those funds can be found starting on Page 125.
Please bear in mind there is no trust fund nor is there a lock box as money is not set aside for future use. Year in and year out more money is spent than taken in and nothing is set aside in any trust. The "Trust Fund" is a total figment of imagination on any kind of reasonable accounting system. Proof of that is simple enough: Just look at assets compared to liabilities, deficit spending, unfunded liabilities, the national debt, and future projections.

GAO Audit


Those still suffering through that massive report will notice the following disclaimers from the Government Accountability Office, starting on page 139 and pretty much continuing for the rest of the document. Following are some of the lowlights:
A significant number of material weaknesses related to financial systems, fundamental recordkeeping and financial reporting, and incomplete documentation continued to (1) hamper the federal government’s ability to reliably report a significant portion of its assets, liabilities, costs, and other related information; (2) affect the federal government’s ability to reliably measure the full cost as well as the financial and nonfinancial performance of certain programs and activities; (3) impair the federal government’s ability to adequately safeguard significant assets and properly record various transactions; and (4) hinder the federal government from having reliable financial information to operate in an economical, efficient, and effective manner. We found the following: Material deficiencies in financial reporting (which also represent material weaknesses)and other limitations on the scope of our work resulted in conditions that continued to prevent us from expressing an opinion on the accompanying consolidated financial statements for the fiscal years ended September 30, 2005 and 2004.

The federal government did not maintain effective internal control over financial reporting (including safeguarding assets) and compliance with significant laws and regulations as of September 30, 2005.

Our work to determine compliance with selected provisions of significant laws and regulations in fiscal year 2005 was limited by the material weaknesses and scope limitations discussed in this report.

Disclaimer of Opinion on the Consolidated Financial Statements

Because of the federal government’s inability to demonstrate the reliability of significant portions of the U.S. government’s accompanying consolidated financial statements for fiscal years 2005 and 2004, principally resulting from the material deficiencies, and other limitations on the scope of our work, described in this report, we are unable to, and we do not, express an opinion on such financial statements.

As a result of the material deficiencies in the federal government’s systems, recordkeeping, documentation, and financial reporting and scope limitations, readers are cautioned that amounts reported in the consolidated financial statements and related notes may not be reliable. These material deficiencies and scope limitations also affect the reliability of certain information contained in the accompanying Management’s Discussion and Analysis and other financial management information—including information used to manage the government day to day and budget information reported by federal agencies—that is taken from the same data sources as the consolidated financial statements.

The Nation’s Fiscal Imbalance

While we are unable to express an opinion on the U.S. government’s consolidated financial statements, several key items deserve emphasis in order to put the information contained in the financial statements and the Management’s Discussion and Analysis section of the Financial Report of the United States Government into context. First, while the reported $319 billion fiscal year 2005 unified budget deficit was significantly lower than the $412 billion unified budget deficit in fiscal year 2004, it was still very high given current economic growth rates and the overall composition of federal spending.

Furthermore, the federal government’s reported net operating cost, which included expenses incurred during the year, increased to $760 billion in fiscal year 2005 from $616 billion in fiscal year 2004. Second, the U.S. government’s total reported liabilities, net social insurance commitments 9 and other fiscal exposures continue to grow and now total more than $46 trillion, representing close to four times current GDP and up from about $20 trillion or two times GDP in 2000. Finally, while the nation’s long-term fiscal imbalance continues to grow, the retirement of the “baby boom” generation is closer to becoming a reality with the first wave of boomers eligible for early retirement under Social Security in 2008. Given these and other factors, it seems clear that the nation’s current fiscal path is unsustainable and that tough choices by the President and the Congress are necessary in order to address the nation’s large and growing long-term fiscal imbalance.

Adverse Opinion on Internal Control

Because of the effects of the material weaknesses discussed in this report, in our opinion, the federal government did not maintain effective internal control as of September 30, 2005, to meet the following objectives: (1) transactions are properly recorded, processed, and summarized to permit the preparation of the financial statements and stewardship information in conformity with GAAP, and assets are safeguarded against loss from unauthorized acquisition, use, or disposition; and (2) transactions are executed in accordance with laws governing the use of budget authority and with other significant laws and regulations that could have a direct and material effect on the financial statements and stewardship information. Consequently, the federal government’s internal control did not provide reasonable assurance that misstatements, losses, or noncompliance material in relation to the financial statements or to stewardship information would be prevented or detected on a timely basis. Our adverse opinion on internal control over financial reporting and compliance is based upon the criteria established under FMFIA. Individual federal agency financial statement audit reports identify additional reportable conditions in internal control, some of which were reported by agency auditors as being material weaknesses at the individual agency level.

David M. Walker
Comptroller General of the United States
December 2, 2005

What the government is willing to admit is rather amazing.
Perhaps they are hoping no one reads these things.
I suggest we would all be better off if these reports were required reading for every high school in the country.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Friday, 10 March 2006

Bubble Busting Phoenix

Congratulations are in order to Bill Buckner for breaking the story about 14,601 Vacant Homes in greater Phoenix area.
Recently, it was reported in the Phoenix market that the number of homes available had jumped from apx3400 homes January 05 to over 30,000 this January. As we watch some of the markets around the country, looking for signs of "the bubble", this number was astounding. As a member of the "Arizona Regional Multiple Listing Service"(ARMLS) I thought I would check for the accuracy of this claim. By the way ARMLS is known to the local realtors as "armless". Funny. In running some stats this morning, there are 33,270 active listings in the MLS. This covers greater Phoenix as well as a bit of outlying area. Another 1,225 are active/contingent. Under contract, but still being marketed for a buyer. There has been a lot of talk of speculation in the Phoenix market, which made me wonder, how many of these homes are vacant. Of the 33,270 active listings, 14,601 are vacant. 14,601, almost half. Wow. Why?? A lot of the "flippers" that bought new homes did not want to put tenants in, so the homes could be marketed as new, never lived in. Move up buyers bought first for convenience/speculation, putting the old home on the market later. People buying 2nd/speculative homes. The high number of vacant homes appears to be the result of this speculative fever that has hit Phoenix, just like many markets.
This has led to the unsustainable increase in home values, as the investors no longer enter the market. And a 10 fold increase in inventory as the speculators decide its time to get out while the gettins' still good. I have no year over year comparison for the vacant homes, or info on what is "normal", just a gut feeling that this doesn't bode well for the market.
Ben Jones picked up the story on The Housing Bubble Blog.
Here are some of the comments:
Ben Jones:
I had tried to ask this MLS if the rumors were true and they wouldn’t reply.

Arizonadude:
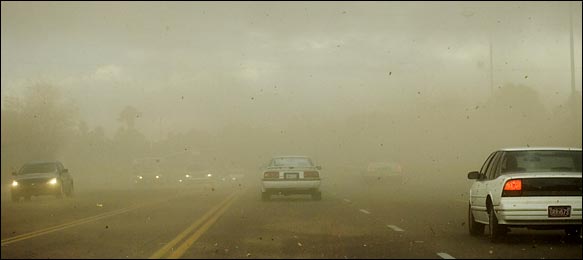
It is a dust bowl here today. The wind is roaring and kicking up dust everywhere from the plowed fields around gilbert. It is an unbelievable scene here right now. Driving home from barnes and noble I was worried my truck would have the paint sand blasted off. There are 50 homes for sale in my subdivision and most are at least 50000 overpriced. More homes keep coming on the market everyday.

AzGolpher:
Just for fun I looked up the number of houses for sale in Queen Creek. 2,200. If you look on Craigslist there are dozens of them and most say “new home, never lived in”. The Craigslist ads are starting to sound desperate.
The New York Times is reporting In Phoenix, Even Cactuses Wilt in Clutches of Record Drought.


PHOENIX, March 9 — Thursday began like the 141 days before it, sunny and crisp, dust settling everywhere except on the record — set again — for the number of days without rain.

"We have cactus dying from lack of water," Mr. Woodard said. "We have well-established mesquite trees that are in a lot of trouble."

Small animals are too dried out to do what comes naturally.
"None of the animals, none of the birds are having offspring this spring. No baby quail, no baby bunnies," Mr. Woodard said.

An alarming result of the drought is the condition of the air. On Thursday, Arizona's Department of Environmental Quality posted its 25th pollution advisory of the winter, a remarkable number. Last winter — the opposite of this one, with abundant rainfall — there were no such days. There is no rain to knock the dust and particles out of the air and wash them away.

"We've just had this large, dry, stagnant air mass hanging over the area since November," said Steve Owens, director of the environmental agency. "It used to be, you'd come to Arizona if you had breathing problems because of the air quality. Now, I think you'd have physicians who would say, 'Don't come to Arizona.' "
What happens if the La Nina dust bowl pattern lasts for another year?
What about 5 years?
Heck, what happens to the water table in 10 years even IF things return to normal?
Perhaps those in the snow belt get the last laugh.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Thursday, 9 March 2006

FED's Geithner On Interest Rate Policy

U.S. monetary policy may need to be tightened sufficiently to offset the downward tug on interest rates from robust official capital inflows, New York Federal Reserve Bank President Timothy Geithner said on Thursday.
Asian central banks have been huge buyers of U.S. government debt in recent years, which analysts say helps explain why long-term bond yields have largely failed to react to a long series of short-term interest rate hikes by the Fed.

Geithner said the downward pressure on bond yields has made financial conditions easier than they would be without the foreign buying.

"Policy would have to act to offset these effects in order to achieve the same impact on the future path of demand and inflation," said Geithner. "To do otherwise would run the risk that monetary policy would be too accommodative."

As vice chairman of the Fed's policy-setting committee, Geithner always votes on interest rates.

Asian countries, especially China and Japan, hold huge amounts of foreign exchange reserves, mostly U.S. dollar-denominated assets.

Geithner said the move toward increased flexibility in the foreign-exchange policies of countries with more rigid currency regimes may not be smooth and gradual but is welcome nonetheless.

"It won't necessarily be smooth and gradual but it's probably healthy for the financial system as a whole," Geithner said in a question and answer session.

Geithner also reiterated his concern about the gaping U.S. external deficit.

He said if the current account gap remained close to 7 percent of gross domestic product, the net U.S. international investment position would "deteriorate sharply."

He said the conditions did not fully exist for a gradual adjustment to such imbalances, and low interest rates may have lulled the country into a false sense of security about its own ability to sustain prolonged deficits.

"This phenomenon (of foreign buying) can act to mask or offset the effects of high levels of present and expected future government borrowing on interest rates, perhaps contributing to a false sense of reassurance that we can continue to run large budget deficits without risk of crowding out private investment and damaging future growth."

Geithner appeared skeptical of conventional explanations for persistent deficits, saying that low U.S. savings and increased productivity only went so far.

"The present magnitude of the U.S. external imbalances seems difficult to reconcile with plausible estimates of future productivity and potential output growth," he said.
Well Hallelujah!
The FED finally figured out foreign treasury buying was influencing US long term interest rates. Bear in mind that I do not think it has had as much impact as others do, but no doubt it has been a factor.

Click on the following link for the full text of NY Fed President Geithner speech:
U.S. Monetary Policy in the Global Financial Environment .

On that note, the Mish telepathic thought lines are now open.

Wow! I am being flooded with questions.
In just three seconds flat I have at least a half dozen distinct questions.
Hmmm I see I have 8 questions, all being asked hundreds of times.
Here they are:
  1. Is the FED that stupid to just be figuring this out?
  2. Who is really responsible for what is happening?
  3. Who is the intended audience of the FED's message?
  4. Are we locking the gates after the horses left the barn?
  5. Why Now?
  6. What direction is the FED looking?
  7. If FED is looking North what direction is the economy headed?
  8. What are the implications?
Let's attempt to answer them one by one.

1)Is the FED that stupid to just be figuring this out?

Although that is certainly possible, a more likely explanation is that the trade deficits and capital inflows are now the most important thing on their minds (for reasons I will explain in just a bit). But there are other possibilities including a "test" of Bernanke. At the heart of the matter and more to the point is a FED full of Hubris that thinks it can create bubbles and deal with any consequence that arise when they pop. On the surface Bernanke is inheriting an economy that seems to be running on all 4 cylinders, where inflation seems to be low, where interest rates seem to be near neutral, and where job growth seems to be reasonably steady enough. Beneath the surface is a completely different story. Whether or not the FED actually believes what they are saying is now no longer of relevance. The FED long ago lost control of credit expansion has succeeded at blowing one bigger bubble after another. The housing bubble is the bubble of last resort and whether or not the FED recognizes what is actually happening at this point in time is simply irrelevant.

2) Who is really responsible for what is happening?

This question is easy enough to answer: The FED was blowing serially bigger and bigger bubbles in conjunction with a president and Congress that long ago lost any semblance of fiscal responsibility. Add in corporate greed and you have a lethal bubble topping mix.

3) Who is the intended audience of the FED's message?

This one is much harder to answer. On the assumption that the FED is not completely brain dead, they see the abyss the US is staring in to. In that case the target audience is corporations, banks, and lending institutions in an attempt to rein in merger mania, IPOs, stock buybacks, spinoffs, leveraged buyouts, and junk bond silliness. Indeed corporations are now (and have been for at least a year) going to the junk bond market to take on debt just for the purpose of stock buybacks. If the FED has a rational thought in their heads it would be to prevent companies from squandering the cash on their balance sheets in the foolish endeavors mentioned above. If corporations squander that cash (and because of pension obligations corporate balance sheets are not as good as they look), then not only will the FED be dealing with a housing bust, they will be dealing with corporate balance sheets as messy as they looked in 2000.

4) Are we locking the gates after the horses left the barn?

Yes. It should be obvious that at least 2/3 of the horses have escape. Still it is better late than never. Perhaps one horse can still be saved: corporate balance sheets. The consumer horse and the housing horse are both beyond redemption.

5) Why Now?

The real question here is "Why not earlier"? Looking back at 2001-2003 when the FED was slashing interest rates like mad, it is entirely likely the FED was attempting to preserve the banking system itself. Banks lent tons of money to "dotcoms" that were imploding left and right as well as to places like Argentina that were defaulting. Banks were likely technically insolvent. Interest rates were slashed and held at absurdly low levels to attempt to bail out banks. This was done on purpose not caring what the aftermath might be. It turns out the aftermath was a housing bubble of enormous proportion, skyrocketing consumer debt, and other associated problems. Still the FED in all their hubris likely feels they saved the day. The housing bubble and the consumer debt bubble will be dealt with like every other bubble: when they pop. The housing bubble is popping now.

6) What direction is the FED looking?

This is sort of a trick question. Judging from all the recent "FedSpeak" the FED sees a robust expansion, increasing jobs, wage expansion, no housing bubble, etc, etc etc, but the bottom line is that after 14 consecutive rate hikes the FED is finally worried about inflation. Simply put, this just does not add up. On the surface it seems the FED is looking North (up). Please review question # 1 at this time. If the FED is really looking North then I simply must change my answer to question #1. It is possible the FED is talking North when they are really looking South.

7) If FED is looking North what direction is the economy headed?

Given the answers to #6 and #1 it just might be hard to say what direction the FED is looking. However, it should be perfectly clear that the FED is talking North. Just as when Greenspan advised people to climb aboard adjustable rate mortgages at THE absolute bottom in interest rates, if the FED appears to be looking North, the prudent investor should be looking South.

8) What are the implications?

This is another tough one. Does the FED have any real clues or not? Notice how I am still questioning my original answer to question #1. What we do know however, is what the FED is actually doing. That is far more important than what the FED is saying. What the FED is doing is hiking into a housing bubble that has clearly popped. I maintain that the FED has long overshot neutral. The collapse of the housing bubble to me is proof. The lagging affect of hikes (and I think at least 3 hikes have not yet been felt), should be enough to give someone pause for concern. But No! Just as the FED way overdid things by slashing rates to 1%, it is all too likely they have way overdone things by hiking. But do they have a choice? The FED must at any costs (consumers be damned) preserve corporate balance sheets to weather the upcoming recession. Notice how I am conveniently once again giving the FED the benefit of the doubt. But wait. I think it is too late. The forces of the FED hiking too far into the face of unprecedented consumer debt and a world wide housing bubble far bigger than the stock market bubble of 1929 will prove too much for this FED. That is the bottom line implication of this mess and going back to question #1 for one last time: No the FED does not see the deflationary credit bust that is coming. The FED in all their hubris will be powerless to stop it.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Wednesday, 8 March 2006

Hot On Homes

This post is a public service announcement in cooperation with the FCC.
In the event of an actual emergency please tune in to the station nearest you.

Following are some newscasters that might be giving the latest HOT News as well as emergency instructions for what steps you might need to take.
 

Hot On D.C. Hot On Denver


Hot On Oklahoma City Hot On Houston


Hot On San Antonio Hot On Dallas/Ft.Worth


Hot On Austin Hot On Dallas/Ft.Worth


Hot On Batton Rouge

Mish is pleased to provide this public service announcement in cooperation with the FCC.
In the event of an actual emergency please tune in to the station nearest you.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/

Tuesday, 7 March 2006

Poole Party (and other short stories)

It's time for a "Poole Party" and other "Words of Wisdom".
----------------------------------------------------------------------------------------------
CNNMoney is reporting Poole sees rising interest rates.

Poole: St. Louis Federal Reserve president says it's better to overshoot mark, then loosen, rather than let inflation get out of control.

Mish: Yeah, let's overshoot both directions. This is just more of the Greenspan philosophy of dealing with bubbles (bubbles the FED helped create) after they pop, then attempting to blow a bigger bubble in the wake of the crash. One more note, Poole sounds as confident about the economy as Greenspan did in March of 2000. We all know what happened then.
-----------------------------------------------------------------------------------------------
The Orlando Sentinel offers this headline Realtor: Home values in Florida to remain solid

Orlando Sentinel: We've seen the real-estate market in Orlando and Florida cool from last year's record pace. Is it going to continue to slow?

Beverly Pindling, Realtor: Continue to slow? I think what may happen -- I don't think you'll see a reduction in [intangible] value; let's put it that way. Value and price are different things. You probably won't see a reduction in value, but maybe in prices, meaning you can pay less but it's worth more. Value is how much that particular piece of property is worth to you.

Mish: Is this part of some new math curriculum sponsored by Bush?
-----------------------------------------------------------------------------------------------
A South Florida Sun-Sentinel reader is claiming Newspaper adding to housing slump in the following letter to the editor:

When one wields great power, as you do, it is imperative that they do it responsibly. This is a great public trust that I think that you are not living up to.

Reporting on the slump in the Florida home sales and prices and the damage caused by Hurricane Wilma can be informative or destructive. I believe that you are no longer reporting news but creating news by repeatedly hammering away at the negative aspects of living in South Florida. I think that what you are practicing now is irresponsible journalism and being part of the cause of the present real estate slump rather than part of the cure.

I'm sure that I speak for many Florida homeowners when I say thank you for doing such a wonderful job in adding to the slump in our housing market.

Mish: Of course there was no problem when the newspaper reported all of those year over year gains. Only good news is allowed. Otherwise shoot the messenger.
-----------------------------------------------------------------------------------------------
From a Dow Jones newswire
David Lereah, NAR's chief economist, said the latest reading shows a flattening out that is in line with "the soft landing we've been expecting" for housing market. "We are at a much more sustainable level of home sales now - a welcome cooling from the super-heated conditions that were driving exceptional price gains," Lereah said.

Mish: This is a soft landing? It seems to me we are in a freefall at 5000 feet somewhere over the grand canyon. When we hit the bottom the landing will be anything but "soft".
-----------------------------------------------------------------------------------------------
Brian O'Connor writing for the Detroit News says Slam the door on big bargains from home foreclosures.

Detroiters love a bargain.
Which is why I am warning you all to stay away from dabbling in foreclosed property.
After reporting last week that home foreclosures have doubled in the state -- and that Wayne County led the nation in foreclosures during January -- I received a stream of e-mails and calls from readers wanting to know where they could snap up the bargains.

The answer: Nowhere.

Equity is wrung out

The fact is that most of these foreclosures would never get to the sheriff's sale if there was any equity left. Either the owners have borrowed too much to buy them in the first place, or they've wrung out every dime of equity in loans, or the home values have declined to the point where the house is -- in the best case -- barely worth more than the bank is owed.

For starters, foreclosed homes don't auction for less than $1 over what the bank is owed, and you have to pay on the spot with a cashier's check. Then you'll wait six months and a day -- under state law -- to see if the homeowner can scratch up the dough to redeem the property or arrange a sale.

If the foreclosed property does finally pass to the successful bidder, chances are good that the property is not in what you'd call "move-in" condition. They're often strewn with trash or stripped down to the walls by desperate or malicious homeowners. In some cases, Schneider notes, bidders offer "cash for keys:" an upfront payment to prompt an owner to move out and walk away.

At the Wayne County Sheriff's auction I witnessed, 379 properties came up for auction. Three received bids, all for just $1 over what the bank had into the place. The rest all went back to the lenders.

The bottom line, it turns out, is that you won't find your dream house at the end of someone else's nightmare.

Mish: You have to read a lot of nonsense to find someone that makes any sense.
My advice.... Listen to Brian O'Connor.

Mike Shedlock / Mish
http://globaleconomicanalysis.blogspot.com/